Volvo Buying vs Leasing: True Costs, Tradeoffs & Which Makes Sense?

Volvo Buying vs Leasing: True Costs, Tradeoffs & Which Makes Sense?
Should you buy your Volvo or lease it? The monthly payment makes leasing look cheaper — and often it is, month to month. But the monthly payment is the wrong number to compare. The right comparison is total cash outlay over the years you actually keep cars, minus the equity you walk away with. Run the math that way, and the answer depends almost entirely on your mileage, how long you keep cars, and how much you value driving something new every few years.
This guide breaks down the true mechanics of a Volvo lease, builds an illustrative dollars-and-cents comparison, and gives you a clear decision framework.
- A lease payment covers depreciation plus a finance charge — you pay for the value the car loses during the lease, not the car itself.
- Typical Volvo lease terms: 36 months, 10,000–12,000 miles per year, excess mileage at $0.20–$0.30 per mile, and residuals around 55–57% on the XC60.
- Buying wins for high or unpredictable mileage, long ownership, customization, and payment-free years after the loan ends.
- Leasing wins for predictable low mileage, driving a new car every 3 years, staying inside the warranty, and avoiding resale risk.
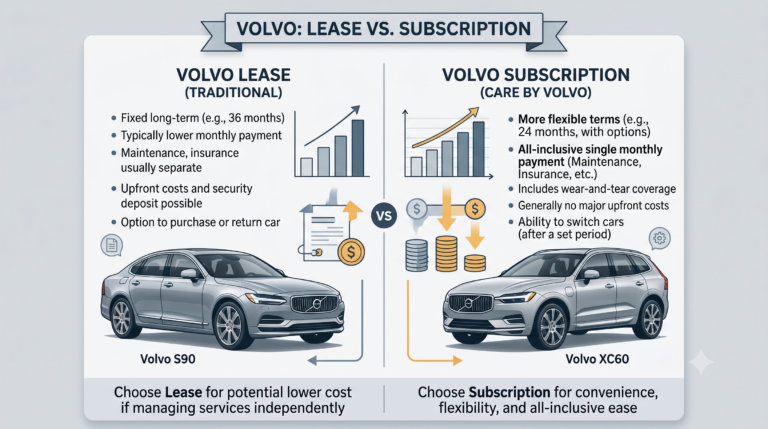
- Care by Volvo — the old subscription alternative — ended in the US on August 1, 2024. It is no longer an option.
- Compare total cost, not monthly payments. An illustrative 6-year scenario below shows how the math actually works.
How a Volvo Lease Actually Works
A lease is not a long-term rental and it is not a purchase with a balloon payment — it is its own contract with its own vocabulary. The five terms that determine everything:
- Capitalized cost: the negotiated price of the car, plus any fees rolled in, minus any down payment or rebates. This is the number you negotiate — just like a purchase price.
- Residual value: what the leasing company predicts the car will be worth at lease end, expressed as a percentage of MSRP. Real-world Volvo examples: a 2024 XC60 Recharge at 55% for 36 months/10,000 miles per year, a 2025 XC60 T8 Plus at 56%, and a 2018 XC60 at 57%. Higher residual = lower payment.
- Money factor: the lease’s finance charge, expressed as a small decimal (e.g., 0.00224 in a documented 2024 XC60 Recharge deal). Multiply by 2,400 to approximate the APR equivalent — 0.00224 × 2,400 ≈ 5.4%.
- Mileage allowance: typically 10,000, 12,000, or 15,000 miles per year. Exceed it and you pay per mile — commonly $0.20 to $0.30 — at lease end.
- Acquisition and disposition fees: expect an acquisition fee around $995 at signing and often a disposition fee at return, plus taxes and registration as your state requires.
Your monthly payment is essentially (capitalized cost − residual) ÷ months for the depreciation portion, plus a rent charge of (capitalized cost + residual) × money factor. Two levers matter most: negotiate the capitalized cost down, and look for manufacturer-supported money factors and residuals — these vary monthly and by region, which is why lease deals change constantly.
One more tool worth knowing: multiple security deposits (MSDs). Some leases let you place refundable deposits to buy down the money factor, reducing the rent charge. It is one of the few genuine “hacks” in leasing — your money comes back at the end.
Buying vs Leasing: The Real Tradeoffs
| Factor | Buying | Leasing |
|---|---|---|
| Monthly payment | Higher (you pay for the whole car) | Lower (you pay for depreciation only) |
| Total cost over 6+ years | Usually lower — payment-free years, retained equity | Higher — perpetual payments |
| Mileage | Unlimited; high mileage is fine | Capped; excess at $0.20–$0.30/mile |
| Equity at the end | You own an asset with real value | None — you hand the car back |
| Always under warranty | No — you outlast it | Typically yes, on a 36-month lease |
| New car every 3 years | Expensive habit | Built into the model |
| Resale/depreciation risk | Yours to bear | The lessor’s problem |
| Customization | Yours to modify | Must stay stock |
| Early exit | Sell anytime | Expensive — early termination fees apply |
| End-of-term condition | Wear is your business | Excess wear charges apply |
Illustrative Math: 6 Years of Lease vs Buy
These are illustrative figures with stated assumptions — not a current offer. Take an XC60 B5 Core with an MSRP of $48,000. Assume a 36-month/10,000-mile lease at 57% residual with a money factor of 0.00150, versus a 60-month purchase loan at 6% APR with no down payment, and assume the buyer keeps the car 6 years.
- Lease: depreciation ($48,000 − $27,360) ÷ 36 ≈ $573/month, plus rent charge ($48,000 + $27,360) × 0.00150 ≈ $113/month — roughly $686/month before tax, plus drive-off fees. Two consecutive leases ≈ $49,400 in payments over 6 years, and you own nothing.
- Buy: $48,000 at 6% APR over 60 months ≈ $928/month, for total payments of about $55,700 — but after month 60 you have a full year with no payment and an asset worth roughly $17,000–$19,000 at year six.
The takeaway is structural, not deal-specific: leasing is cheaper per month but more expensive per decade, because the buyer eventually stops paying and keeps an asset. The lessee pays forever and keeps nothing. If you keep cars 6+ years, buying almost always wins on total cost. If you would have bought a new car at year three anyway, the gap narrows dramatically — and the lease’s warranty coverage and zero resale hassle start to look like real value.
The Mileage Question Decides More Than You Think
Be brutally honest about your annual mileage before signing anything. At 10,000 contracted miles per year, just 3,000 extra miles annually costs $600–$900 per year in excess-mileage charges at $0.20–$0.30 per mile — enough to erase a lease’s monthly-payment advantage. Unpredictable mileage (new job, new commute, road-trip habit) is the single best argument for buying: miles are free when you own the car.
What About Business Use?
For business owners and the self-employed, leasing has a genuine tax advantage in many jurisdictions: lease payments on a business-use vehicle are often deductible as an operating expense, which is simpler than depreciating a purchased asset. Rules vary by country and tax situation — this is a question for your accountant, not your dealer — but it is the one scenario where leasing can win on pure economics even for high-mileage drivers.
A Note on Care by Volvo
Volvo’s all-inclusive subscription program, Care by Volvo — one monthly payment covering the car, insurance, and maintenance with the ability to swap vehicles — was discontinued in the United States (and Europe) on August 1, 2024, and Volvo has said it is paused for the foreseeable future. It should not be presented as a current alternative to buying or leasing. Existing subscribers were offered credits toward a purchase or lease when the program wound down.
Which Path Fits You?
Verdict
Buy if you drive a lot, keep cars a long time, or want the lowest lifetime cost — ownership’s payment-free years and retained equity are unbeatable. Lease if your mileage is low and predictable, you want a new Volvo every three years, and you value warranty coverage and zero resale hassle. Either way, negotiate the capitalized cost, compare total cash outlay rather than monthly payments, and never sign a lease without doing the excess-mileage math honestly.
Frequently Asked Questions
Is it cheaper to buy or lease a Volvo?
Per month, leasing is usually cheaper; over six or more years, buying is usually cheaper. In our illustrative scenario, two consecutive 36-month leases cost about $49,400 over six years with no equity, while buying cost about $55,700 in loan payments but left roughly $18,000 of equity — a net cost near $37,700.
What is a good residual value on a Volvo lease?
Recent real-world XC60 examples cluster around 55–57% for 36 months and 10,000 miles per year (55% on a 2024 XC60 Recharge, 56% on a 2025 XC60 T8 Plus, 57% on a 2018 XC60). Higher residuals mean lower payments; residuals vary by model, term, mileage, and month.
What happens if I go over my lease mileage?
You pay an excess-mileage charge at lease end — commonly $0.20 to $0.30 per mile on Volvo leases. Driving 3,000 miles over per year can add $600–$900 annually, so honest mileage estimates matter more than the monthly payment.
Can I end a Volvo lease early?
Usually yes, but it is expensive: early termination typically means paying the remaining payments plus fees, or buying out the lease. Leasing is a poor fit if your circumstances might change mid-term.
Is Care by Volvo still available?
No. Care by Volvo, the all-inclusive subscription program, ended in the US and Europe on August 1, 2024, and Volvo has said it is paused for the foreseeable future. It is not a current alternative to buying or leasing.
What are multiple security deposits (MSDs) on a lease?
Refundable deposits you place at lease signing to reduce the money factor, which lowers the monthly rent charge. You get the deposits back at lease end, making MSDs one of the few genuinely low-risk ways to cut lease costs — where the program is offered.
Sources
- TrueCar — Volvo XC60 lease guide (lease mechanics, mileage and damage terms): https://www.truecar.com/volvo/xc60/lease/
- Leasehackr Forum — 2024 XC60 Recharge lease deal data (36 mo / 10k mi, 55% residual, MF 0.00224): https://forum.leasehackr.com/t/deal-check-2024-volvo-xc-60-recharge-ultimate-dark/565136
- InsideEVs — “Volvo Is Killing Its Care By Volvo Subscription Service” (ended Aug 1, 2024): https://insideevs.com/news/733597/volvo-car-subscription-over/
- Automotive News — Care by Volvo profitability and subscriber history: https://www.autonews.com/volvo/care-volvo-profitable-80-subscribers-are-new-brand